Forgiveness in 2026
Student loan forgiveness in 2026: what is left, when it comes, and who pays the tax.
Four ways a federal balance still gets forgiven this year, the clock on each, and what four borrowers would have forgiven on IBR against RAP. Nothing here is a promise. Every rule links to its source, and the ranking counts forgiveness and the tax on it in what you pay all in.
Rank every plan for me, free Ten questions, two minutes, your own numbers.
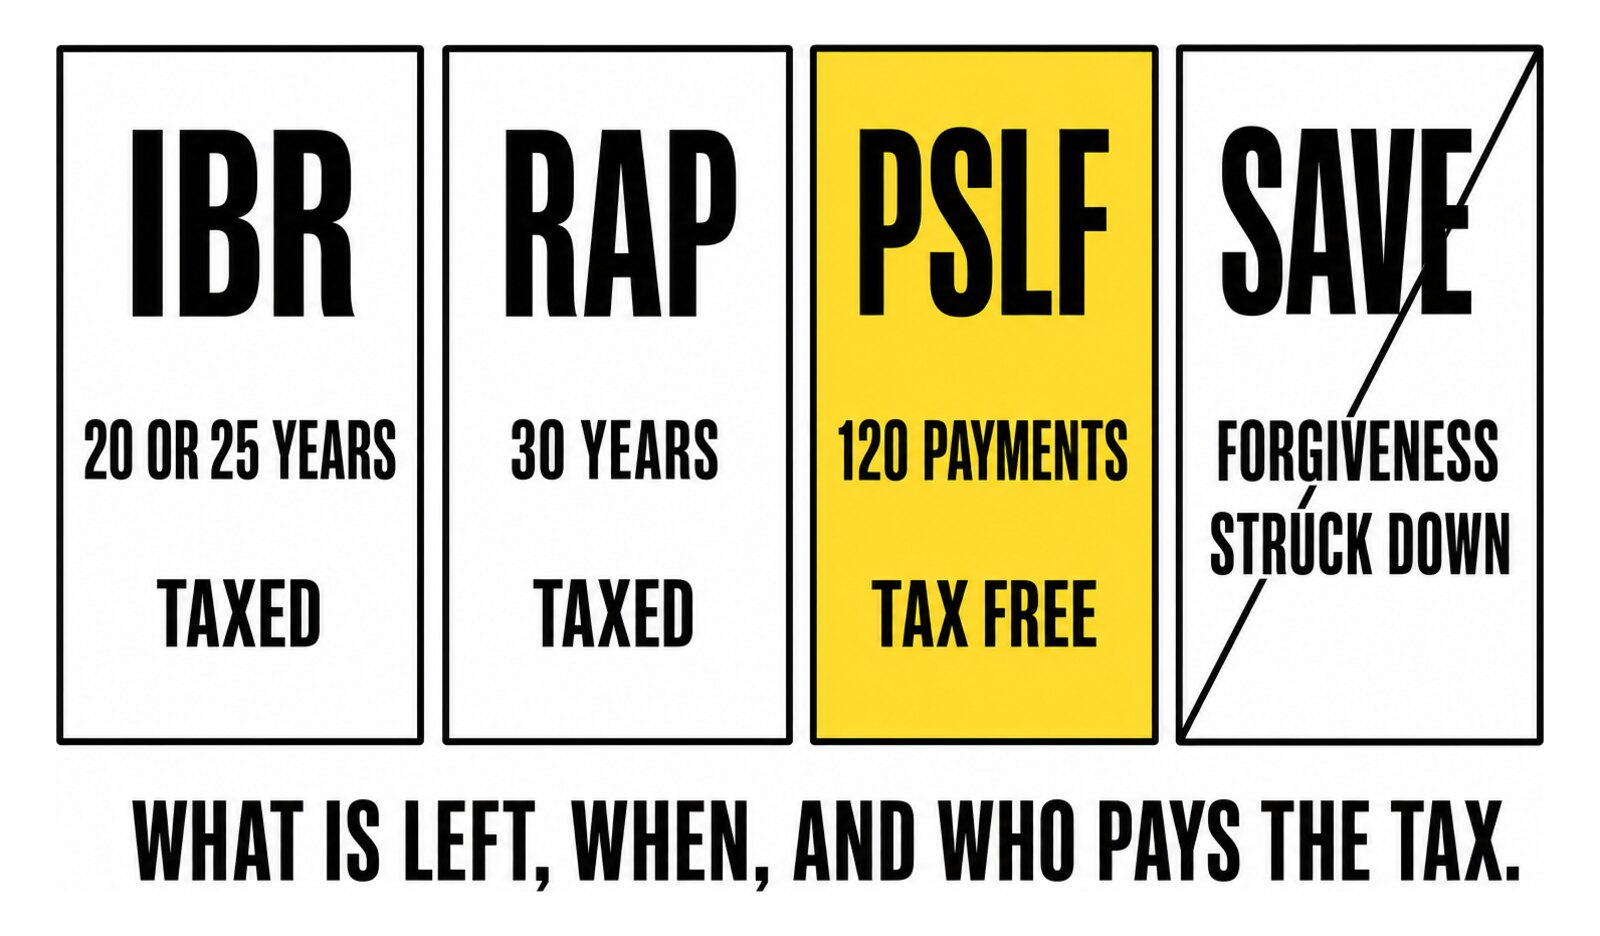
The four paths, and the one that closed
- IBR
- After 20 years of qualifying payments for new borrowers, 25 for earlier borrowers. Earlier payments under IBR, PAYE, ICR and SAVE count. Months in RAP do not. Forgiveness after 20 or 25 years is taxable federal income from 2026. PSLF forgiveness is not.
- RAP
- The remaining balance is forgiven after 360 qualifying payments, 30 years. Months in RAP do not count toward IBR's 20 or 25 year forgiveness if you later switch. Forgiveness after 30 years is taxable federal income in the year it happens, under the law since January 1, 2026. PSLF forgiveness is not.
- PSLF
- 120 qualifying payments on a qualifying plan while working full time for a government or nonprofit employer. The forgiven balance is tax free. RAP, IBR, PAYE and ICR count; Graduated and Extended do not, except a month whose payment matches the 10-year Standard amount.
- PAYE and ICR
- After 20 years of qualifying payments. Both plans close by July 1, 2028, so their clocks end on IBR or RAP.
- SAVE
- Its forgiveness never happened: the courts blocked it and the plan is being wound down. Months in the SAVE forbearance since August 1, 2025 earn no credit toward forgiveness or PSLF.
Four borrowers: what IBR and RAP would forgive
The engine runs each plan month by month at a flat income. A big forgiven balance is not a win: it comes with a tax bill that year, and the plan that forgives the most is often the one that cost the most to get there.
| Borrower | On IBR | On RAP | #1 plan | All in on #1 |
|---|---|---|---|---|
| $38,000 income, $27,000 in loans | $18,536 after 20 years, tax about $4,078 | nothing, paid off in 19 years | Standard 10-year | $36,790 |
| $46,000 income, $58,000 in loans | $70,069 after 20 years, tax about $15,415 | nothing, paid off in 26 years | Income-Based Repayment | $78,746 |
| $55,000 income, $48,000 in loans | $9,238 after 20 years, tax about $2,032 | nothing, paid off in 18 years | Standard 10-year | $65,404 |
| $85,000 income, $95,000 in loans | $26,385 after 20 years, tax about $5,805 | nothing, paid off in 16 years | Standard 10-year | $129,445 |
Assumes single, a family of one, first loan after July 1, 2014, a 6.5% rate, no public service, income rising 3% a year with the poverty line following the CBO inflation forecast (the studentaid.gov calculator's assumptions), and a 22% tax on any taxable forgiveness. Monthly figures are the first year: income-driven payments are recalculated from income every year, Graduated steps up every two years, Standard and Extended stay fixed. Your own numbers change the order.
Four things people get wrong
The tax bill is real
From 2026, a balance forgiven under IBR, RAP, PAYE or ICR is federal taxable income in the year it happens. Only PSLF forgiveness is tax free. The ranking assumes 22% and shows it on every plan.
Forbearance months count toward nothing
Interest has run in the SAVE forbearance since August 1, 2025, and those months earn no credit toward any forgiveness. Every month on a qualifying plan is one on the clock; every month waiting is not.
RAP time does not count toward IBR
Months in RAP do not count toward IBR's 20 or 25 year forgiveness if you switch later. Pick the plan you can stay on, not the one with the lowest first bill.
Public service is a different clock
PSLF counts payments, not years, and needs qualifying employment throughout. Our PSLF guide ranks the plans for three public servants and lists the two things to do this month.
Forgiveness, the tax on it, and the plan that gets you there cheapest.
The free ranking runs every plan you qualify for on your income and loans, month by month, with forgiveness and its tax counted. Every position is free, with the math; the kit with the pre-filled form is $29.
Rank my plans, freeSources
- Income-driven repayment plans Federal Student Aid
- 34 CFR 685.209, income-driven repayment plans Code of Federal Regulations
- The Repayment Assistance Plan, In Focus IF13075 Congressional Research Service
- Public Law 119-21, the 2025 reconciliation act (student loan title) Congress.gov
- Public Service Loan Forgiveness Federal Student Aid
- Next steps for borrowers enrolled in the SAVE Plan (press release) U.S. Department of Education
- Court actions and the end of SAVE Federal Student Aid
- Topic 456, student loan interest deduction IRS
- PSLF changes in 2026 Tate Law