Closing: ends by July 1, 2028
Income-Contingent Repayment (ICR)
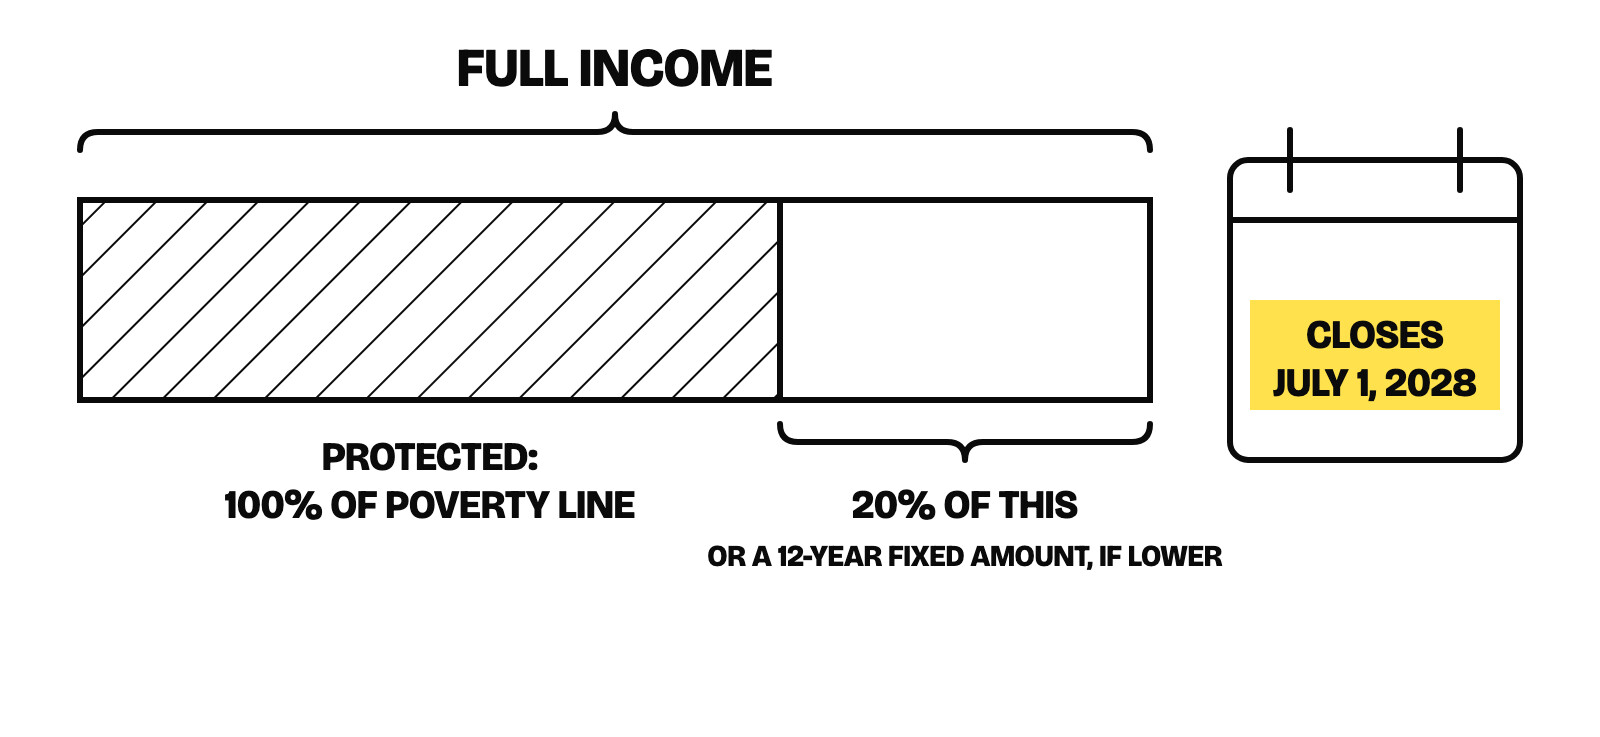
The only income-driven plan for consolidated Parent PLUS loans; 20% of discretionary income or a 12-year fixed amount, whichever is less.
See where it ranks for you, free Two minutes, your own numbers, every plan side by side.
- Payment
- The lesser of 20% of discretionary income (AGI minus 100% of the poverty guideline) and what a 12-year fixed plan would charge, adjusted by an income factor.
- Who qualifies
- Direct Loans. The only income-driven option for Parent PLUS loans, and only after consolidation into a Direct Consolidation Loan. Otherwise a path for borrowers already on it.
- Forgiveness
- After 25 years of qualifying payments.
- Interest
- Unpaid interest accrues; no subsidy.
- PSLF
- Qualifies.
- Taxes
- Forgiveness is taxable federal income from 2026, except under PSLF.
- How to apply
- Online at studentaid.gov/idr, after consolidating Parent PLUS loans.
- Leaving it
- Everyone on ICR moves to IBR or RAP by July 1, 2028; consolidated Parent PLUS borrowers should confirm their path with the servicer before then.
- Dates
- Closes no later than July 1, 2028.
Good for
- Consolidated Parent PLUS loans with no other income-driven option
Watch out
- The highest payment share of any income-driven plan
- Ends in 2028
Where ICR lands for you depends on your numbers.
Right Repay runs every plan on your income, household, balance and loan dates, ranks them on all-in cost, and shows the math. Every position is free, with the math; the kit to switch is $29.
Rank my plans, freeSources
- 34 CFR 685.209, income-driven repayment plans Code of Federal Regulations
- Income-driven repayment plans Federal Student Aid
- Public Law 119-21, the 2025 reconciliation act (student loan title) Congress.gov
Which plan is right for you depends on your income, your balance and your loans' dates.
Rank every plan for me, freeThe other plans
- Repayment Assistance Plan (RAP)New, since July 1, 2026
- Income-Based Repayment (IBR)Open, permanent for loans made before July 2026
- Standard 10-yearThe default when you choose nothing
- Graduated 10-yearOpen
- Extended 25-yearOpen, for more than $30,000 in Direct Loans
- Pay As You Earn (PAYE)Closing: ends by July 1, 2028
- Tiered StandardNew, for loans made on or after July 1, 2026
Guides
- SAVE is ending: what to do in your 90 daysThe dates, the options, what the default costs
- RAP vs IBRRule by rule, with numbers for four borrowers
- PSLF and the SAVE exitWhich plans count, which to pick
- Married: file jointly or separatelyThe same couple, both ways
- Parent PLUS loansWhat is still open, what consolidating changes
- Your servicer's noticeMOHELA, Nelnet, Aidvantage, Edfinancial
- How the ranking worksThe rules, the math, what it assumes, what it never does
- RAP calculatorThe formula, the brackets, four borrowers' payments
- IBR calculatorDiscretionary income, the 10% or 15%, the cap
- IDR calculator, every planRAP, IBR, PAYE and ICR on the same income
- Forgiveness in 2026What is left, when it comes, who pays the tax
- The best repayment planRanked for four borrowers, and what the default costs
- How to apply for RAPWhat to have ready, the screens, the answers